
The Bank of Israel on Saturday rejected Prime Minister Benjamin Netanyahu's suggestion that cryptocurrency could help the country circumvent potential international financial sanctions, warning that digital currencies cannot provide an alternative route around such restrictions and urging the government to focus instead on preventing sanctions and preserving Israel's economic ties with its trading partners.
"Cryptocurrencies cannot serve as a means of circumventing sanctions," the central bank said in an unusually direct response to the prime minister's proposal, which has drawn sharp criticism from senior economists, former government officials and financial experts.
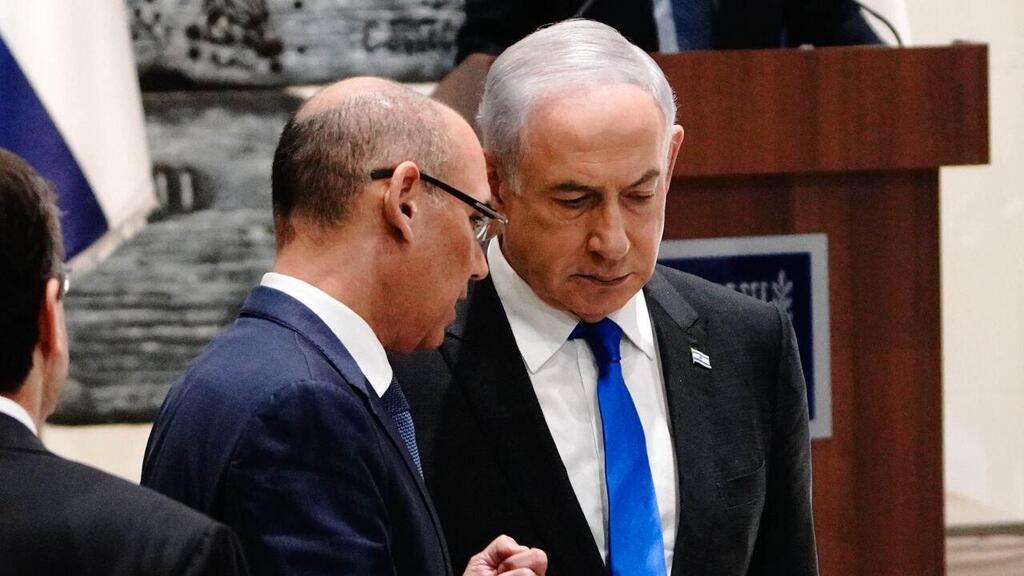
Bank of Israel Governor Prof. Amir Yaron and Prime Minister Benjamin Netanyahu
(Photo: Shalev Shalom)
"The right course for Israel's economy is to maintain its economic relationships with our main trading partners and focus on preventing sanctions and their negative impact on the economy," the bank said. "This issue falls within the responsibility of the political leadership, and it should take action to advance that goal."
The statement followed Netanyahu's remarks in an interview with Israel's Economy Channel, in which he said Israel must prepare an alternative financial system capable of operating around potential international banking sanctions. Asked whether cryptocurrency and blockchain technology could offer a solution, Netanyahu said they were among the options being considered and claimed he had already ordered a plan to be prepared.
However, officials in Israel's economic ministries said they were unaware of any such initiative. Even senior figures in the Prime Minister's Office said they knew of no team working on the proposed plan.
Netanyahu, however, showed no sign of backing down from his cryptocurrency proposal despite the Bank of Israel's criticism. Speaking to Channel 14, the prime minister said: "I hear the objections and take them into account. I thank the Bank of Israel for its advice. I listen, but I do what I think is right."
The central bank's intervention came amid a growing backlash from leading economic figures who warned that attempting to circumvent sanctions through cryptocurrency could undermine Israel's financial stability, damage its international standing and accelerate the departure of investors and businesses.
Yair Avidan, former supervisor of banks at the Bank of Israel, said Netanyahu's proposal reflected a fundamental misunderstanding of how international financial restrictions operate.
"Blockchain is not a solution for circumventing sanctions," Avidan said. "Moving a transaction onto a blockchain network or using a digital token does not make sanctions disappear, does not create an alternative economy, does not override legal prohibitions and does not change the obligations of the parties involved."
He explained that blockchain-based payments still require cooperation from banks, payment providers and trading partners, all of which remain subject to financial regulations and sanctions compliance requirements. Without their participation, the technology cannot provide a practical alternative to the international financial system.
Avidan acknowledged that blockchain technology could help maintain payment systems during emergencies or infrastructure disruptions, but stressed that such applications should not be confused with a mechanism for evading sanctions.
"The threat of sanctions is real," he said, warning that restrictions could damage banking relationships, trade, credit and investment, potentially raising the cost of living. Preparing for that possibility, he argued, requires responsible policymaking, maintaining international trust and protecting commercial ties.
Former Finance Ministry director-general Yarom Ariav went further, describing Netanyahu's remarks as a serious warning sign for Israel's economic future.
"Sanctions are not an inevitable force of nature. They are the direct result of failed policies," Ariav said. He warned that proposing financial workarounds placed Israel alongside internationally isolated regimes such as Iran and recalled the economic isolation of South Africa during apartheid.
Ariav, who headed the Finance Ministry during the 2008 global financial crisis, warned that the prime minister's remarks could shake financial markets, threaten Israel's credit rating and accelerate capital flight. Foreign investors, he said, could increasingly avoid a country perceived as becoming disconnected from international banking, while highly skilled workers could seek more stable economies abroad.
Professor Yair Zimon warned that a cryptocurrency-based alternative economy would threaten Israel's access to international banking networks, foreign investment and global trade.
Israel's high-tech industry, venture capital sector and international commercial relationships depend on established financial infrastructure, including global payment systems such as SWIFT, he said. Replacing those arrangements with volatile, insufficiently regulated digital currencies would expose businesses and households to substantial financial risks.
Zimon warned that pursuing such a policy could trigger an exodus of technology companies, capital flight, a sharp depreciation of the shekel and rising inflation, while severely disrupting imports of essential goods, energy and medicine.
"Turning Israel's stable financial system into one based on volatile, unregulated currencies would be tantamount to gambling with the fate of the entire economy," he said.
The criticism also extended to the cryptocurrency industry itself. Tomer Sharoni, CEO of Adresable, a company specializing in cryptocurrency intelligence and identification technologies, said digital assets offer no immunity from international sanctions.
"Changing the means of payment does not turn a prohibited transaction into a permitted one," Sharoni said, noting that cryptocurrency transactions leave digital records that can be traced to users, including in financial activity originating in Russia and Iran.
He emphasized that the ability to transfer money electronically does not guarantee that foreign businesses will accept payments, continue trading with Israel or invest in its economy. Cryptocurrency infrastructure, he said, should be developed to strengthen Israel's integration into global markets rather than as an escape route from sanctions.
Economist Professor Manuel Trajtenberg, a former chairman of Israel's National Economic Council, argued that the country's growing international isolation was not inevitable. He rejected the suggestion that American military assistance must necessarily come to an end, noting that Washington has strategic interests in maintaining cooperation with Israel's defense establishment.
Trajtenberg also drew a connection between Netanyahu's cryptocurrency proposal and his earlier vision of Israel becoming a self-reliant "Sparta," warning that neither offered a genuine solution to the country's economic challenges.
The Israeli High-Tech Headquarters, representing dozens of senior technology executives, warned that accepting economic isolation as inevitable could devastate an industry dependent on international investment, open markets and cross-border business. Companies could close, investment could dry up and operations could move overseas, the group said.
Former economy and planning minister Professor Shimon Shetreet similarly warned that sanctions affecting Israeli banks could spread economic damage across multiple industries. Professor Eran Yashiv of Tel Aviv University argued that Netanyahu's remarks could themselves intensify concerns in international financial markets and potentially worsen the very sanctions the prime minister was proposing to circumvent.
Their warnings reinforced the central message of the Bank of Israel's response: cryptocurrency may have legitimate technological and financial applications, but it cannot replace the international relationships on which Israel's economy depends. Rather than preparing to operate outside the global financial system, the central bank said, Israel's political leadership should concentrate on preventing the restrictions that could threaten those relationships in the first place.