
The Energy and Infrastructure Ministry has published the final report of the Dayan Committee, the interministerial panel charged with reviewing natural gas policy and strengthening the country’s energy security through 2048.
The report attempts to answer some of the biggest questions facing Israel’s energy sector: how much gas the country is likely to need, how much should remain available for domestic consumers, how much can be exported, what level of competition exists between suppliers and how Israel should prepare for the day its offshore reserves begin to run down. The committee’s base scenario puts cumulative domestic demand through 2048 at about 515 billion cubic meters, while the final policy leaves the domestic reservation requirement at 440 BCM.
But beneath the recommendations lies a series of unresolved disputes between the Energy Ministry and officials at the Finance Ministry, Competition Authority, environmental authorities and other state bodies.
The timing matters as well. The report has arrived during an election period, with elections for the 26th Knesset scheduled for October 27, meaning many of the most consequential long-term policy decisions are likely to fall to the next government.
What about competition?
One of the most persistent structural concerns in Israel’s gas market is concentration.
The issue centers heavily on U.S. energy giant Chevron, which operates both Leviathan and Tamar, Israel’s two largest gas reservoirs. Chevron holds 39.66% of Leviathan and 25% of Tamar, while the two fields together account for the overwhelming majority of reserves listed in the committee’s earlier field-by-field data.
That does not mean Chevron literally owns 90% of Israel’s gas. But its position as operator and significant shareholder in both dominant reservoirs has repeatedly raised competition concerns.
The Competition Authority has been explicit. Its energy team has argued that the combination of cross-ownership and a single operator across Tamar and Leviathan prevents optimal competition and recommended examining legislation that could ultimately require Chevron to exit one of the two reservoirs.
The final Dayan recommendations do not adopt that structural separation. The decision reflects, among other considerations, a desire to preserve regulatory stability and continue attracting large international energy companies.
That leaves the next government with a familiar dilemma: whether greater regulatory intervention would improve competition and potentially restrain prices, or discourage investment in a market that depends on capital-intensive offshore exploration.
Pressure to export before enlarging the pie
The Energy Ministry continues to emphasize the economic and diplomatic value of gas exports, particularly to Egypt and Jordan. Ministry officials have argued that exports help justify investment in expanding production while generating significant state revenue and strengthening regional energy ties.
The dispute is not over whether Israel should export gas at all. It is over how much can safely leave the country before sufficient supply is guaranteed for domestic consumers decades into the future.
(Photo: Jeff Chiu\AP)
That disagreement is visible in the report’s export mechanism. The Energy Ministry would continue to play the central role in granting export permits while consulting a broader interministerial forum.
Critics argue that such a system puts too much weight on securing and expanding exports before guaranteeing a sufficiently large surplus for the Israeli market.
The State Comptroller has also warned that export decisions must account for the full long-term implications for domestic supply and future import costs. Its review noted that 49% of the gas produced in Israel in 2024 was exported to Egypt and Jordan and urged a broader government examination of the export approval mechanism.
Banking on an optimistic scenario
A second major question concerns gas that has not yet been discovered.
The committee’s policy assumes that continued exploration could add resources to Israel’s existing offshore reserves. That is crucial because the margin becomes considerably tighter if future discoveries fail to materialize.
The final report estimates proven and contingent reserves at about 826 BCM at the start of 2026 while projecting base-case domestic demand of roughly 515 BCM through 2048.
The problem is that exploration is inherently uncertain. Even if additional gas exists beneath Israel’s economic waters, finding and developing commercially viable reservoirs requires international companies willing to accept large geological, financial and security risks.
And even a successful discovery does not provide immediate supply. Developing another producing reservoir can take years, meaning a field discovered later in the decade would not necessarily solve a short- or medium-term shortage.
That makes future discoveries an important upside scenario, but a risky foundation on which to build energy security.
A report that arrived after major deals
The timing of the committee’s work creates another problem.
The Dayan Committee was established in February 2024 and published its draft recommendations in April 2025, but its final conclusions emerged only in September 2026. In the meantime, major export decisions and expansion plans moved ahead.
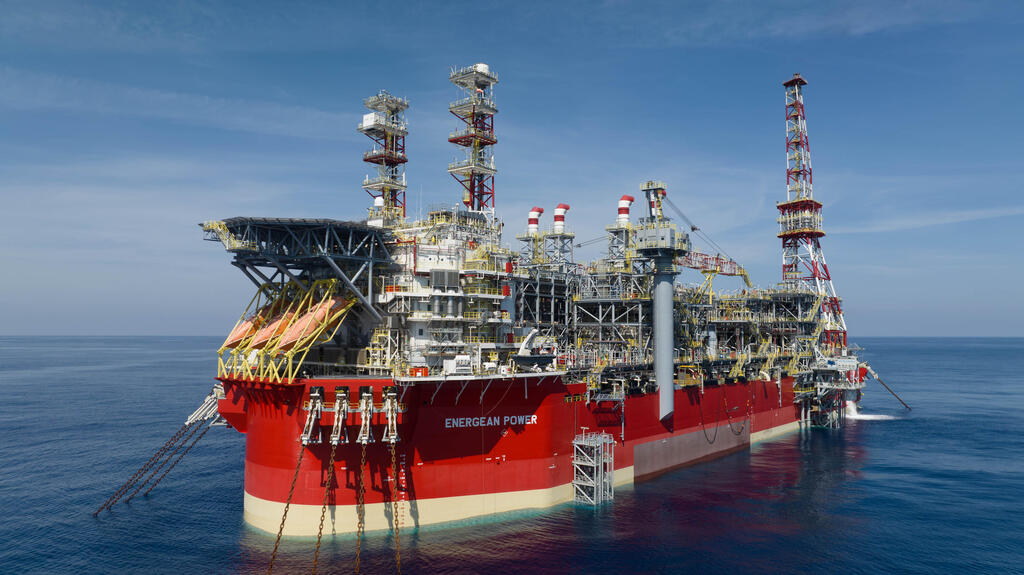
Chevron and its Leviathan partners, for example, approved a major expansion of the field in January 2026, with three additional offshore wells and infrastructure intended to raise total gas delivery capacity to about 21 BCM annually toward the end of the decade.
The result is that the final policy framework is arriving after some of the strategic choices it was meant to inform have already begun reshaping the market.
That raises a practical question for the next government: how much room remains to change course after long-term export commitments and multibillion-dollar investments have already been made?
The dispute inside the committee
Perhaps the most important part of the Dayan report is not where officials agreed, but where they did not.
One example is the principle that Israel should maintain excess gas production capacity above expected domestic demand. The report accepts the need for a supply cushion in principle but does not impose the hard numerical requirement sought by some professional bodies.
Finance Ministry and Competition Authority representatives pushed for daily surplus capacity of roughly 13% to 20% above demand. The Electricity Authority sought at least 10%, while the Energy Ministry opposed setting a fixed figure.
A similar divide surrounds the amount of gas that must be preserved for the domestic market. The final report keeps the reservation requirement at 440 BCM, while the Finance Ministry, Competition Authority and Environmental Protection Ministry supported raising it to at least 515 BCM, roughly matching the committee’s base-case estimate of domestic demand through 2048.
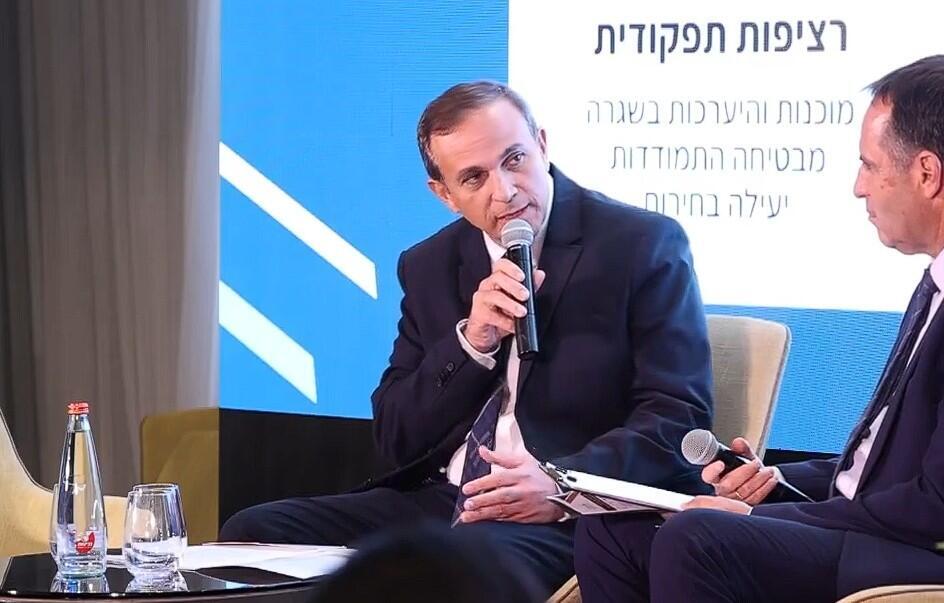
Energy Ministry Director General Yossi Dayan
(Photo: Shmulik Davidpur)
Those disagreements matter because Israel is simultaneously planning for increased electricity demand, new gas-fired power generation and an expansion of renewable energy, while large data centers and the electrification of transportation and industry could alter demand forecasts.
That is why one of the report’s most consequential recommendations may ultimately be its call for a comprehensive national energy plan.
Rather than treating gas exports, power stations, renewable energy, storage and future imports as separate policy questions, such a plan would force the government to decide what Israel’s energy mix should actually look like over the coming decades.
A dedicated natural gas team would also be tasked with developing measurable standards for energy security, examining gas import and storage infrastructure and proposing regulatory and legislative changes.
The fundamental question is therefore larger than how many BCM Israel should export next year. It is whether the country can turn a valuable but finite resource into a coherent long-term energy strategy before the comfortable surplus it enjoys today begins to narrow.