
Six weeks before Israel’s election, the National Economic Council has unveiled a sweeping proposal to eliminate mandatory employee pension contributions until age 40, a change that could increase younger workers’ take-home pay by about 6%.
The plan, published Monday by the council in the Prime Minister’s Office and headed by Prof. Avi Simhon, would leave employers’ pension contributions fully intact. Workers would remain insured, but no pension deduction would be taken from their salaries until they turn 40, when the current mandatory contribution would resume in full.
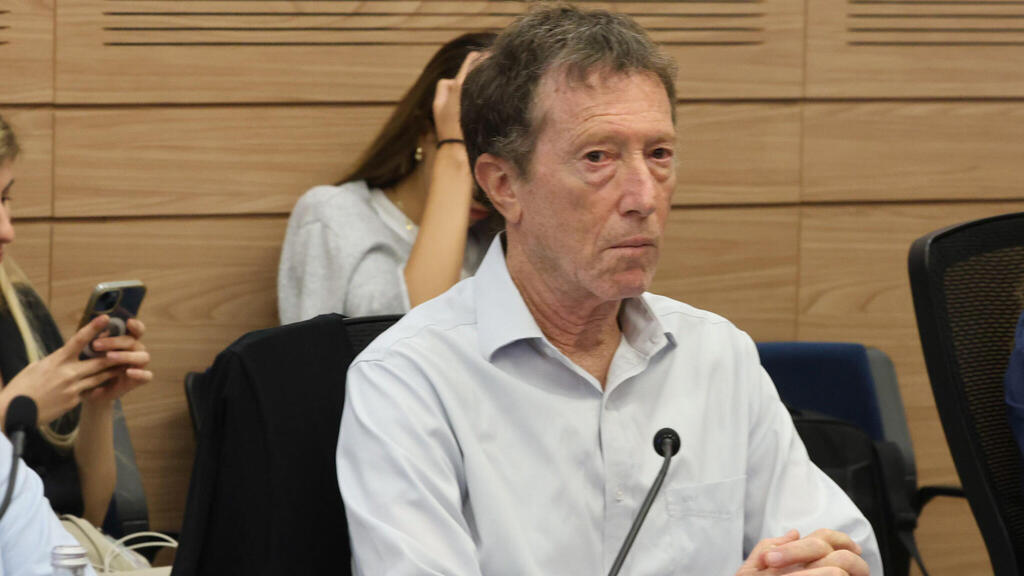
Prof. Avi Simhon
(Photo: Danny Shem Tov, Knesset Spokesperson’s Office)
Economic officials have criticized both the substance of the proposal and the timing of its release, warning that it could encourage younger workers to sacrifice long-term savings for higher disposable income today. Its publication in the middle of an election campaign has also prompted concerns that the proposal could serve as an appeal to younger voters.
Still, the proposal is not merely an election-season talking point. It is a substantive policy being seriously considered within the National Economic Council and is likely to be raised for discussion after the election regardless of which parties form the next coalition.
The proposal is based on research conducted by Simhon and Avraham Zupnik of the National Economic Council examining how income changes over a representative worker’s lifetime, from the first years of employment through retirement. Using Central Bureau of Statistics data and actuarial simulations, the study examined expected pension savings and retirement income by gender and income quintile.
Israel’s mandatory pension system was introduced through a 2008 extension order requiring employers and employees to contribute to pension savings at uniform rates, regardless of a worker’s age or stage of life.
According to the council’s research, many workers are expected to receive retirement income similar to, or even higher than, their net monthly earnings during much of their working lives. The effect is particularly pronounced among lower-income workers, for whom the state old-age benefit makes up a larger share of retirement income.
The council argues that this creates a mismatch between when workers have money available and when they need it most. Major expenses such as starting a family, raising children and making mortgage payments tend to be concentrated in the earlier working years, when earnings have not yet reached their peak.
Under the proposal, eliminating the employee contribution before age 40 would improve disposable income during those years while, according to the council, still leaving workers with an adequate level of retirement income. The change would serve only as the default, meaning workers who wished to continue contributing before 40 could do so voluntarily.
Critics, however, warn that many younger workers would likely choose the immediate increase in take-home pay without fully accounting for the potentially significant loss in pension savings decades later. They say the cumulative effect could have serious financial consequences for entire generations of workers.
The proposal comes after another initiative promoted by Simhon aimed largely at younger couples whose mortgage payments had risen sharply because of the Bank of Israel’s higher interest rates. That plan met fierce opposition from the Bank of Israel and senior economic officials and was ultimately removed from the government agenda on the day it was due to be discussed. It was never brought back for approval.