
Who has not imagined climbing into a car and simply saying, “Take me to the theater,” or “Drive me to the stadium,” then turning to the news or eating dinner while the vehicle handles the road? In theory, the same car could later head out alone to pick up a child from taekwondo practice.
That dream has been around for decades, and in recent years it seemed almost within reach. Yet for all the excitement, autonomous driving has so far delivered far more disappointment than transformation.
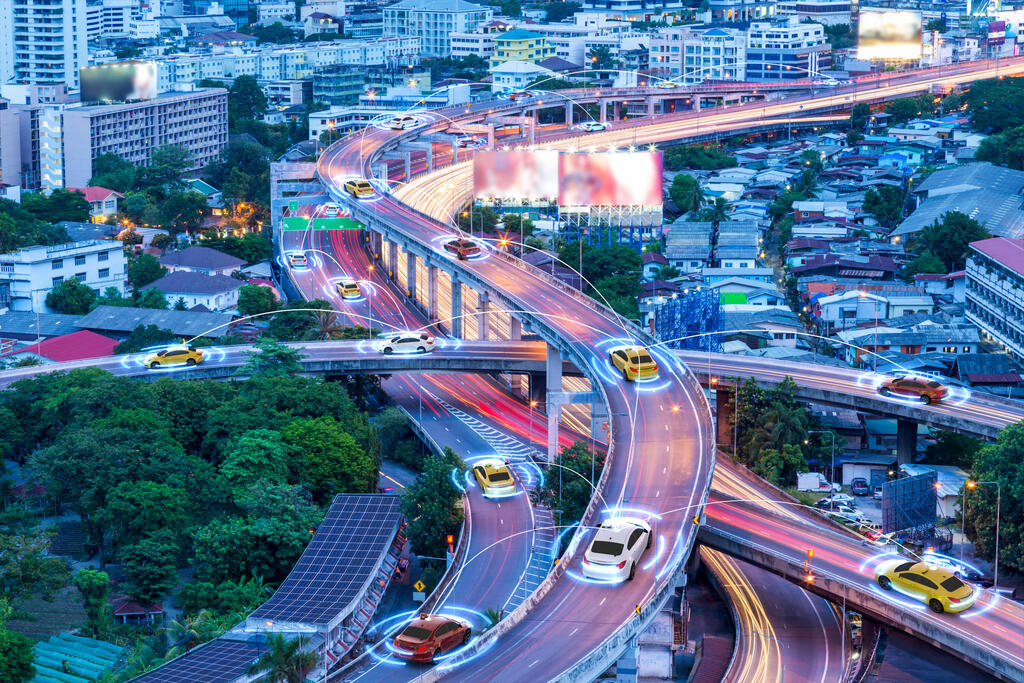
The concept dates back to experiments by General Motors as early as 1939, but the modern race took off over the past decade as virtually every major automaker and technology company poured money into self-driving systems. More than $100 billion has been invested across the industry, yet many of the most ambitious projects collapsed. The number of fully autonomous vehicles operating worldwide is still estimated at only about 10,000.
Apple’s Project Titan became one of the most striking examples. The company spent roughly $10 billion attempting to build what was envisioned as the iPhone of the automotive world: a futuristic lounge on wheels without a steering wheel or pedals. The project was shut down in 2024 after years of development when the technology proved less mature than expected.
Others suffered similar fates. Uber invested around $1 billion in autonomous taxis before abandoning the project in 2020 after a fatal crash. Lyft spent hundreds of millions of dollars before closing its autonomous-driving operation in 2021. General Motors’ Cruise launched a commercial robotaxi service but halted operations after a serious accident. Argo AI, backed by Ford and Volkswagen with about $4 billion, shut down in 2022 after heavy losses.
Still, development never stopped. The clearest commercial successes so far have been robotaxi services in restricted areas. Google-owned Waymo, Amazon’s Zoox and Tesla operate autonomous taxi services in some US cities, while Uber offers such a service in Abu Dhabi and several Chinese companies operate in parts of China. But these remain geographically limited systems rather than vehicles capable of driving freely from any point to any destination.
To understand why the industry stalled — and why experts now believe it may finally be approaching a turning point — ynet spoke with Eran Rosenberg, who leads NVIDIA’s Physical AI Inception activities in Europe and the Middle East; Omer Keilaf, founder and CEO of Innoviz; and Ram Machness, CEO of Arbe Robotics.
Keilaf said the gap between expectations and reality largely came from companies rushing to market before the technology was ready. “There were quite a few projects that failed because different players made poor choices about platforms and sensors,” he said. “GM’s Cruise is an example of a company that rushed to market before it was ready, and that hurt confidence in the entire sector. Waymo, by contrast, works slowly and responsibly. The way they operate, I would feel comfortable sending my child in one of their cars.”
Cameras, radar and lidar
One of the industry’s biggest arguments is over how an autonomous vehicle should “see” the world around it.
Tesla has drawn criticism for choosing a camera-based approach, while many rivals rely on a combination of cameras, radar and lidar. Israeli companies are major players in those additional sensing technologies: Arbe develops high-resolution radar, while Innoviz specializes in lidar, which uses lasers to create a three-dimensional map of the environment.
Machness said public tolerance for mistakes by autonomous systems is far lower than for human drivers.
“Our first instinct is that we drive with our eyes, so perhaps a car can drive with cameras,” he said. “But as humans, we make many mistakes and miss things. We are not willing to accept an autonomous vehicle killing people.”
Arbe’s high-definition imaging radar is designed to generate independent three-dimensional sensing with fewer false alerts, including in poor weather conditions.
“In high-definition imaging radar, there are two leading companies in the world, and both are Israeli,” Machness said. “This technology provides a reliable picture of the environment even in difficult weather.”
Keilaf argues that lidar fills another critical gap. Cameras can become blocked by dirt, rain or mud, while lidar and radar provide alternative layers of perception.
“If a vehicle drives through a mud puddle and the camera gets dirty, that becomes a serious safety problem,” he said. “Automakers need to prove that the system remains safe even in cases like that. Lidar and radar make it possible to deal with those situations and ensure safe driving.”
AI moves into the physical world
The next technological leap may come from what the industry calls Physical AI.
Unlike generative AI systems such as GPT, Claude and Gemini, which are designed primarily to understand and generate language, Physical AI models are trained to understand the real-world physics of objects, motion and cause and effect.
Rosenberg presented NVIDIA’s in-vehicle computing platform, which processes information from multiple sensors in real time. He said NVIDIA sees autonomous vehicles as part of a much broader transformation.
“Physical AI is a trillion-dollar market,” he said. “Jensen Huang, NVIDIA’s CEO, always says that everything that moves will become autonomous.”
The company is developing what are known as world models, designed to understand concepts such as friction, momentum and the rigidity of materials. These models do not simply detect objects; they are intended to understand why those objects behave as they do and what the vehicle should do in response.
“We developed models that see the environment and explain causality — what the vehicle sees and why it decides to move right or left,” Rosenberg said.
A major obstacle remains data. Language models can train on enormous quantities of material from the internet, but autonomous systems need data about rare physical events that may barely exist in real-world driving records.
NVIDIA’s answer is simulation.
“Our computers can generate extremely high-quality simulated data, for example an elephant walking onto a road, in order to train systems for the most extreme scenarios,” Rosenberg said.
China as the industry’s crystal ball
When it comes to commercial adoption, the experts see China as the industry’s main accelerator.
“The Chinese market is a kind of crystal ball for the automotive industry,” Keilaf said. “The Western market understands the challenge posed by the pace in East Asia.”
Machness believes fully autonomous private ownership will begin there first. “In the West, we estimate that we will see privately owned autonomous vehicles around 2030,” he said. “But in the Chinese market, we believe it could happen by the end of next year.”
Keilaf said Innoviz sensors are already being integrated into several autonomous projects due to reach the road soon. One major project involves Volkswagen, which is expected to operate robotaxis in six cities, including Munich, Oslo and locations in Florida. Another project involves Daimler’s autonomous-truck operations.
For now, however, robotaxis and autonomous trucks are likely to remain ahead of fully autonomous privately owned cars.
From cars to defense
The companies building sensors for autonomous vehicles have also discovered another market hungry for the same technology: defense.
Expertise in radar and lidar is increasingly being applied to autonomous combat vehicles and systems designed to detect and defeat explosive drones.
“In the past six months, about 95% of my time has been devoted to discussions about explosive drones,” Keilaf said. “The threat requires autonomous defense systems capable of locating a drone precisely within five seconds, and lidar provides the accurate identification needed to neutralize it quickly and at low cost.”
Machness said demand is also rising for high-resolution radar capable of detecting small aircraft and drones.
The shift highlights how technologies originally developed for passenger vehicles are becoming useful across robotics, defense and other autonomous systems.
The long road to the self-driving car
The autonomous-driving industry is now moving away from the era of extravagant experiments and toward a smaller group of companies, more standardized computing platforms and sensor combinations that may finally be technologically mature enough for broad deployment.
In the near term, consumers are likely to encounter autonomous taxis in limited areas and perhaps growing fleets of autonomous trucks. Fully autonomous private cars will require further advances in AI, additional proof of safety and falling hardware costs.
But if those pieces come together, the impact could extend far beyond the auto industry.
A truly autonomous private vehicle would challenge years of transportation planning aimed at moving people out of private cars and onto public transit. If driving no longer requires a driver, demand for car travel could actually rise.
Children, older adults and people who do not currently drive could all become road users in a way they are not today. A car would no longer need its owner inside it at all; it could drive across town to pick someone up and then continue to another destination.
That creates a new question for transportation planners: if autonomous vehicles eventually give almost everyone access to personal road travel, how will cities make room for them all?
After years of failed promises, the autonomous car is not here yet. But if the industry’s latest predictions prove correct, 2027 may be the year the technology finally begins to move from demonstration to reality — first in China, and only later in much of the West.