
Three years of war have left deep scars on the State of Israel and its citizens — trauma whose effects will remain with us for many years. And yet, in at least one area, Israel has managed to demonstrate resilience: the economy, and particularly the financial markets.
Israel’s gross domestic product grew by nearly 10% during this period. The Tel Aviv Stock Exchange’s flagship index, the TA-35, surged by no less than 130%. The TA-125, which includes the 125 shares in the TA-35 and TA-90 indices, jumped 120%.
Those gains are impressive in their own right, and also compared with the world’s largest stock market. Since the eve of October 7, the S&P 500 has risen by about 80% — roughly 40 percentage points less than the TA-125. The Nasdaq climbed by about 101% over the same period — around 19 percentage points less.
An important caveat: This does not mean the war did not damage the Israeli economy. Its cost was extremely high. According to a Bank of Israel estimate, the cumulative loss of output from the start of the war through the end of 2025, compared with the prewar growth trend, totaled about 177 billion shekels — equivalent to 8.6% of annual GDP.
Even so, the economy’s ability to grow and the stock market’s ability to surge during a prolonged war are worth examining. There have been countries that grew rapidly during and after wartime, including the United States during World War II and the Korean War, but in those cases most of the fighting took place far from their territory.
The war that began with the October 7 massacre unfolded on several fronts but also directly affected Israeli territory and the home front. Despite that, the Israeli economy proved resilient, while financial markets posted sharp gains.
How did it do so? That is a good question. There appears to be a range of reasons, and it is doubtful that any one of them alone would have been sufficient. We will not go into a full analysis here, but will briefly suggest several possible explanations, chief among them painful experience: The Israeli economy has learned to recover quickly from security shocks.
The economy’s starting point may also have helped. Israel entered the war with an excellent debt-to-GDP ratio of about 60%. War spending and expanded mobilization pushed it to nearly 70%, as discussed below.
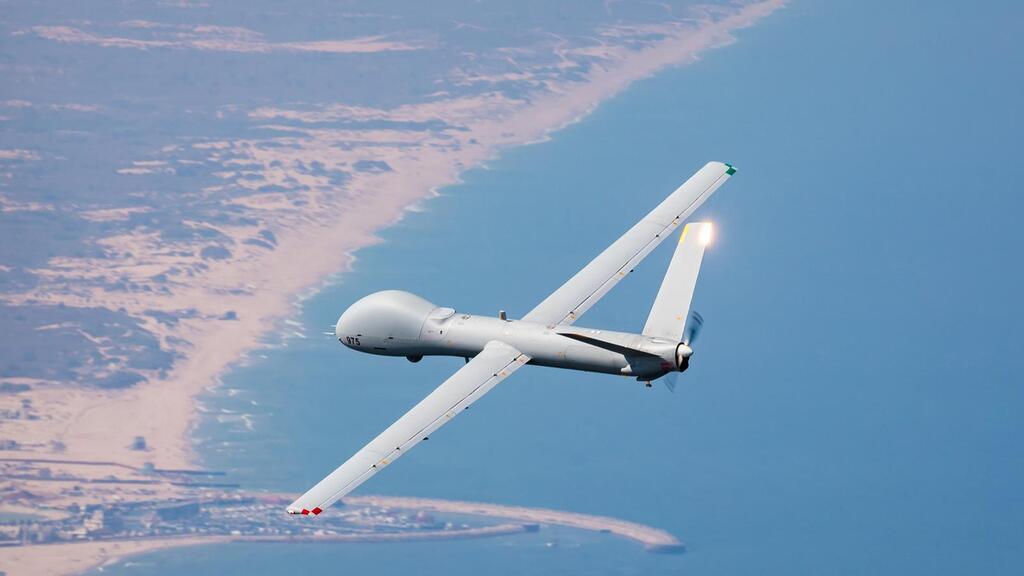
A Hermes 900 built by Elbit
(Photo: Elbit Systems)
The high-tech sector, one of Israel’s main growth engines, was able to continue much of its activity even under wartime conditions, in part because of the ability to work remotely and because of its exposure to global markets. The defense industries and cybersecurity activity within the tech sector provided a boost of their own, thanks to heavy state demand and Europe’s military buildup following Russia’s invasion of Ukraine.
On high-tech’s contribution, Yoni Panning, chief strategist at Mizrahi-Tefahot, said: “The locomotive of the Israeli economy was, of course, the main driver of growth, with current exports of services nearly 30% higher than before the war. There is also a question about its dynamics. As with geese that lay golden eggs, there is quite a bit of mystique surrounding the ‘diet’ that deserves the credit: the state of education, Israel’s international standing and investment in Israeli high-tech. In practice, it is difficult to say that any of those driving factors has improved.”
Panning added that the low point in services exports came, unsurprisingly, around November 2023, when the data showed a 9.2% annual decline. A month later, the figure had already returned to slightly positive territory.
“And despite all the rounds of fighting, the missiles, the closure of education systems and so on, in only eight of the 32 months of war for which data are available did we see an annual contraction in this series. On top of that, of course, one must add more moderate phenomena, such as defense exports, which account for roughly 25% of services exports and have naturally benefited from the global situation. But as with high-tech, no less important in the bottom line has been Israel’s own internal momentum, however that has manifested itself.”
Meitav chief economist Alex Zabezhinsky offers his own explanation for the stock market rally. According to him, between mid-2024 and April of this year, the TA-125 delivered a return 70% higher than the MSCI World index, which is composed largely of U.S. stocks, and overall, since the start of the war, it has delivered a return 40% higher.
“Such a large advantage has not been seen since 2009. How do you explain a gap like that? In no sense did Israel’s situation improve during the period in question, neither in security nor strategically. The conclusion may be that financial markets are a kind of machine for measuring changes in expectations. They do not react to the existing situation. The highest returns are born precisely at moments when fear is at its maximum. That happened in the financial crisis, during COVID and also here during the war.”
Tel Aviv Stock Exchange: Who rose, by how much, and who lagged
The stock exchange raced ahead even though it is not heavily weighted toward technology. Quite a few high-tech companies are traded on it, but their weight in the leading indices is not large. Most Israeli high-tech companies are privately held, and the largest among those that are public are traded mainly overseas.
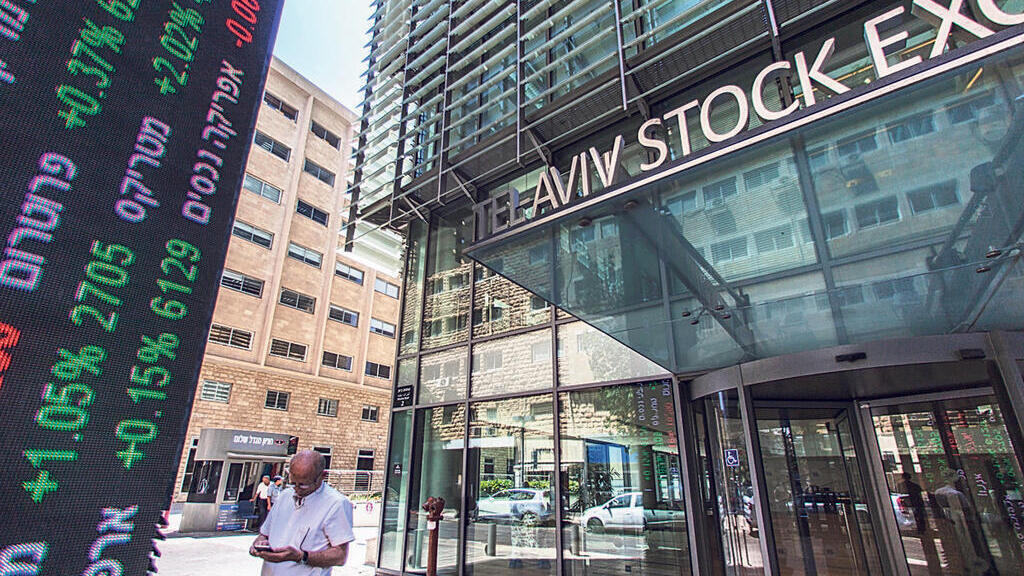
Tel Aviv Stock Exchange
(Photo: Getty Images)
It is therefore worth examining who drove the exchange forward and who contributed less.
Among the sector indices, the TA-Insurance index stood out above all others, soaring 490% over the past three years. The increase came, among other things, against the backdrop of the high-interest-rate environment and consistent improvement in earnings, a combination that drew extensive investment into the sector from foreign investors.
The TA-Banks index also outperformed the TA-125, surging by more than 140%. TA-Industry rose 120%, TA-Technology climbed 105%, the TA-Oil and Gas index gained 85%, while TA-Real Estate lagged far behind with an increase of 55%.
The most notable absentce from the comparison is the TA-Defense index. The reason is not its performance, but its age: The index was launched only in November 2025 and therefore does not have a sufficiently long “trading history” for the current summary.
The stocks that make it up posted sharp gains over the period reviewed, thanks to factors already mentioned — enormous demand from the state and a global arms race.
Above them all stood NextVision. Shares of the miniature camera manufacturer soared 965% over the past three years, the sharpest increase among TA-35 and defense stocks. Elbit Systems, Israel’s largest publicly traded defense company, completed a gain of 200% over the three years of war.
The five largest insurance companies in Israel are included in the TA-35. Harel led them with a surge of 658%, placing it second in the index. Menora Mivtachim rose 585%, Phoenix 440%, Clal Insurance 425% and Migdal 355%.
Among bank shares, Leumi led with a jump of 177% since the start of the war. Hapoalim rose 172%, Mizrahi-Tefahot 100%, Discount 95% and First International 75%.
Another standout near the top of the TA-35 was the stock of the Tel Aviv Stock Exchange itself, which soared 635% and took third place in the index, against the backdrop of the boom in the local market and sharp growth in exchange activity, reflected in trading volumes.
In 2023, average daily turnover in the equities market, including ETFs, stood at 1.998 billion shekels. In 2024, it rose 10% to 2.198 billion shekels.
The following year, turnover jumped 57%. Average daily turnover in 2025 stood at 3.45 billion shekels. In the first half of 2026, it had already reached 5.7 billion shekels, an increase of about 65% compared with the 2025 average.
The sharp rise in trading volumes and stock indices drove the Tel Aviv Stock Exchange share price sharply higher and led to its inclusion in the TA-35 in the latest semiannual index update in May.
Before concluding this section, it is worth noting the only two TA-35 stocks that ended the three-year period with negative returns: ICL lost 18% over the period, while Nice fell 46%. During that period, at the end of 2024, CEO Barak Eilam, who had turned it into a successful international company, stepped down.
Government bond yields
The fighting since October 2023 led to an unprecedented wave of government debt issuance to finance defense spending, pushing yields higher against the backdrop of a growing deficit and rising risk premium. At the same time, the corporate debt market showed resilience and record demand from institutional investors, which led to a rapid narrowing of credit spreads.
The immediate economic need to finance the costs of fighting, reconstruction of communities and payments to reservists forced the Finance Ministry to massively increase the volume of bond issuance. The large supply of government debt, alongside the sharp rise in the state’s structural deficit, created persistent pressure on the domestic yield curve.
Downgrades of Israel’s credit rating by international rating agencies translated into an increase in the country’s risk premium
(Photo: Reuters)
At the same time, downgrades of Israel’s credit rating by international rating agencies translated into an increase in the country’s risk premium, as reflected in credit default swaps.
Investors demanded higher yields, which reflect lower bond prices, in order to hold government debt, especially longer-dated bonds. This led to high volatility and price declines in government bonds, while only expectations of monetary stability from the Bank of Israel and interest rates stabilizing around 4% provided the market with partial support.
The yield on Israel’s 10-year government bond rose from about 4.3% on the eve of the war in October 2023 to a peak of more than 5.1% during 2024. It has now stabilized at around 4.08%.
Since October 7, 2023, the yield on the 10-year U.S. Treasury has also followed a sharp and volatile upward trend, rising from about 4.7% at the time to a peak of roughly 5.34% as of early October 2026. The rise to the highest levels since 2002 was driven mainly by persistent inflation, rising energy prices and growing investor concerns about the widening U.S. fiscal deficit.
As in the United States, the yield on Britain’s 10-year government bond also has risen sharply and erratically since October 7, 2023, climbing from around 4.6% at the time to about 5.24%-5.42% as of early October 2026.
The rise to the highest levels since 2007 was driven by a combination of persistent inflationary pressures in Britain, surging global energy prices and growing market concerns over a widening deficit and the Bank of England’s continued high-interest-rate policy.
Corporate debt and Tel Bond indices: Record demand and institutional liquidity
In complete contrast to the volatile trend in government bonds, the corporate debt market demonstrated exceptional resilience thanks to the high liquidity of Israeli institutional investors, including pension funds, provident funds and education funds.
Institutional investors looking for local investment alternatives with built-in protection generated record demand for bond offerings by large Israeli companies. Leading companies, particularly banks and stable income-producing real estate companies, took advantage of market appetite and raised tens of billions of shekels.
As a result of the strong demand, credit spreads — the gap between corporate bond yields and those on equivalent government bonds — narrowed rapidly after widening slightly at the beginning of the war and reached historically low levels. This reflected market confidence in the repayment capacity of large domestic companies and made corporate bonds one of the highest-yielding and most stable components of investment portfolios over the period.
“The Israeli bond market reached October 7 after a prolonged period of weakness. The debate over the judicial overhaul had already led, in the months before the war, to declines in Israeli assets and an increase in the risk premium, so the market’s starting point was relatively weak. Despite that, after the initial response to the war, a long process of strengthening in Israeli assets and falling yields actually began, sometimes even during periods when yields globally were moving in the opposite direction," according to Saar Weintraub, deputy chief investment officer for provident funds and pensions at Altshuler Shaham.
“The watershed moment was the pager incident. Until then, the market was still carrying much of the concern that had built up in the months before the war and during it. After that event, a perception began to take hold that something fundamental was changing in the regional balance of power, and that security developments could reshape the map of the Middle East. From that point, we saw a significant change in Israel’s pricing — local assets strengthened, the shekel strengthened and later the bond market also posted very strong performance, with yields in Israel often falling precisely when global markets were moving in the opposite direction.
“In recent months, the Bank of Israel’s interest-rate cut was added to that, further strengthening the domestic interest-rate market. For a considerable period, we saw clear outperformance by the Israeli bond market relative to bond markets around the world. The local market benefited both from an improvement in perceptions of Israel’s risk and from an interest-rate path that became more supportive.
“Recently, the picture has become more complex. The trend in the U.S. bond market has turned very negative, and U.S. yields have risen to levels that make it difficult for the Israeli market to remain detached. Therefore, despite interest-rate cuts in Israel and the relative strength shown by the local market, we are already seeing upward pressure on yields in Israel as well. Added to that is political uncertainty ahead of the election campaign, so at this stage it is more difficult to continue the same sharp decline in yields we saw earlier. After a period in which the Israeli bond market clearly outperformed global markets, it is now being influenced to a much greater extent by the global trend.”
The strength of the shekel
The foreign exchange market tells a story that would have been difficult to imagine in the first days of the war, when the dollar surged above 4 shekels and the Bank of Israel took an unprecedented step, announcing that it would sell tens of billions of dollars to stabilize the market.
Three years later, not only have most of those dollars remained in the Bank of Israel’s foreign currency reserves, but the dollar is now trading at around 3.08 shekels — almost 20% below its level on the eve of the war.
(Photo: Shutterstock)
On the eve of the war, the dollar traded at 3.8388 shekels, after the shekel had weakened significantly during 2023 against the backdrop of political uncertainty.
When the war broke out, the shekel weakened rapidly. On October 9, the dollar jumped nearly 3% to 3.95 shekels, and on October 26 it reached a peak of 4.078 shekels — an increase of 6.2% in less than three weeks.
On October 9, the Bank of Israel announced a program to sell up to $30 billion in foreign currency, along with the possibility of providing up to $15 billion through swap transactions, with the aim of moderating volatility and preserving market functioning.
In practice, however, only a small part of the firepower allocated by the Bank of Israel was needed. In October, the bank sold $8.2 billion and in November another $338 million. From December onward, it no longer sold foreign currency. At the same time, the shekel reversed direction. By the end of December, the dollar stood at 3.6008 shekels — down 11.7% from its October peak and below its level on the eve of the war.
According to Shmuel Katzavian, chief strategist at Discount Bank, the very announcement by the Bank of Israel was significant, even if it did not immediately halt the shekel’s decline. “The Bank of Israel’s announcement did not cause the shekel to strengthen in the days that followed, and the shekel continued weakening almost until the end of October. At the same time, the announcement itself was highly important because it signaled to the market that the bank was prepared to intervene as necessary and greatly reassured investors.”
According to Katzavian, the intervention moderated the initial weakening of the shekel after the Hamas attack, but it was not the factor that drove the currency’s strengthening over the following three years. He describes the three years as a movement from “the initial surprise and fear among investors” toward an improvement in Israel’s strategic position in the eyes of the markets and a return of the structural factors supporting the shekel.
According to him, while the initial response to October 7 included foreign investors selling Israeli assets and a sharp weakening of the shekel, as the war progressed, security developments came to be viewed more positively by investors.
This pattern was especially evident around Operation Rising Lion. In the week before the operation, the shekel actually weakened amid uncertainty and fear of a direct confrontation with Iran, but after the operation began it strengthened sharply.
According to Katzavian, a pattern emerged of “concerns before the event and relief once the event materializes. A similar pattern also characterized the period before the ground entry into Gaza, before Operation Northern Arrows against Hezbollah and the initial phase of Operation Roaring Lion. The shekel responded positively to the implementation of proactive Israeli security moves that ended periods of waiting and uncertainty.”
In 2024, the shekel did not show a consistent trend, and the Bank of Israel described the exchange rate as volatile and heavily influenced by geopolitical developments. By 2025, a clearer appreciation trend had formed. The shekel strengthened by about 6% against the dollar n the first half of the year and by a similar rate in the second half.
The pattern Katzavian described was particularly pronounced during Operation Rising Lion. On June 13, the day the operation began, the dollar reached an intraday peak of 3.68 shekels. By June 16, it had already fallen to 3.46 shekels — a drop of more than 3% in a single trading day.
Not just the war: The other forces pushing the shekel higher
Yossi Menashe, founder and co-CEO of Altshuler Shaham Financial Services, said that “one of the central lessons of the past three years is that the security situation alone is not enough to explain the direction of the currency.”
Alongside the decline in the risk premium, institutional activity is a significant factor in the foreign exchange market. Pension funds, provident funds and insurance companies hold large volumes of assets overseas. When the value of those assets rises and dollar exposure increases, they sell dollars and buy shekels in order to maintain their desired hedge ratio. As a result, gains on Wall Street can create upward pressure on the shekel.
In 2025, institutional investors sold a net $20 billion in foreign currency, and in the second quarter of 2026 alone they sold another $13.8 billion. In the same quarter, foreign residents also sold a net $6.4 billion in foreign currency.
According to Menashe, institutional activity is joined by other structural forces, including foreign currency inflows from exports, especially from the technology sector, the domestic savings base and foreign capital entering Israel. “Over time, these forces can be more significant than the immediate response to a security or political headline,” he said.
It is not just a weak dollar
Part of the dollar’s decline against the shekel can also be explained by the weakening of the U.S. currency globally, but only part of it.
Between October 6, 2023, and October 1, 2026, the dollar fell 19.8% against the shekel, while the Dollar Index, which measures the U.S. currency against a basket of major currencies, declined by only 4.1% over the same period. At the same time, the euro also weakened by 14.4% against the shekel.
In other words, even after accounting for the global weakness of the U.S. currency, there remains a very significant appreciation of the shekel itself.
On May 29, 2026, the representative dollar exchange rate was set at 2.81 shekels. Compared with the October 2023 peak of 4.078 shekels, that represented a decline of nearly 31%. Since then, the dollar has risen 9.3% from that low and is now trading at around 3.08 shekels.
According to Katzavian, April and May saw the sharpest two-month strengthening of the shekel against the dollar ever recorded, with the exception of the final two months of 2023.
But unlike at the end of 2023, when the movement was a correction after the sharp depreciation at the outbreak of the war, this time the appreciation came after a prolonged period in which the shekel had already been strengthening.
According to Katzavian, a rate of 2.81 shekels to the dollar had already become “too extreme” relative to the underlying economic conditions.
From a central bank selling dollars to one buying them
One figure that illustrates just how much the foreign exchange market has changed over the past three years is the activity of the Bank of Israel itself.
In October 2023, the bank sold billions of dollars to stabilize the market. By the second quarter of 2026, it had become a net buyer of foreign currency, purchasing about $1.8 billion.
In less than three years, the market moved from fears of a sharp depreciation to a situation in which the shekel was trading at some of its strongest levels in years.